RefE-038
Entered
Figures3 min · 622 words
Working paper
Okeanis Eco Tankers Beats by $2.94 as EPS Hits $7.67
Okeanis Eco Tankers posted Q3 EPS of $7.67 versus a $4.73 consensus on $501.5 million revenue, and raised its dividend 33% to $7.00 per share payable December 1.
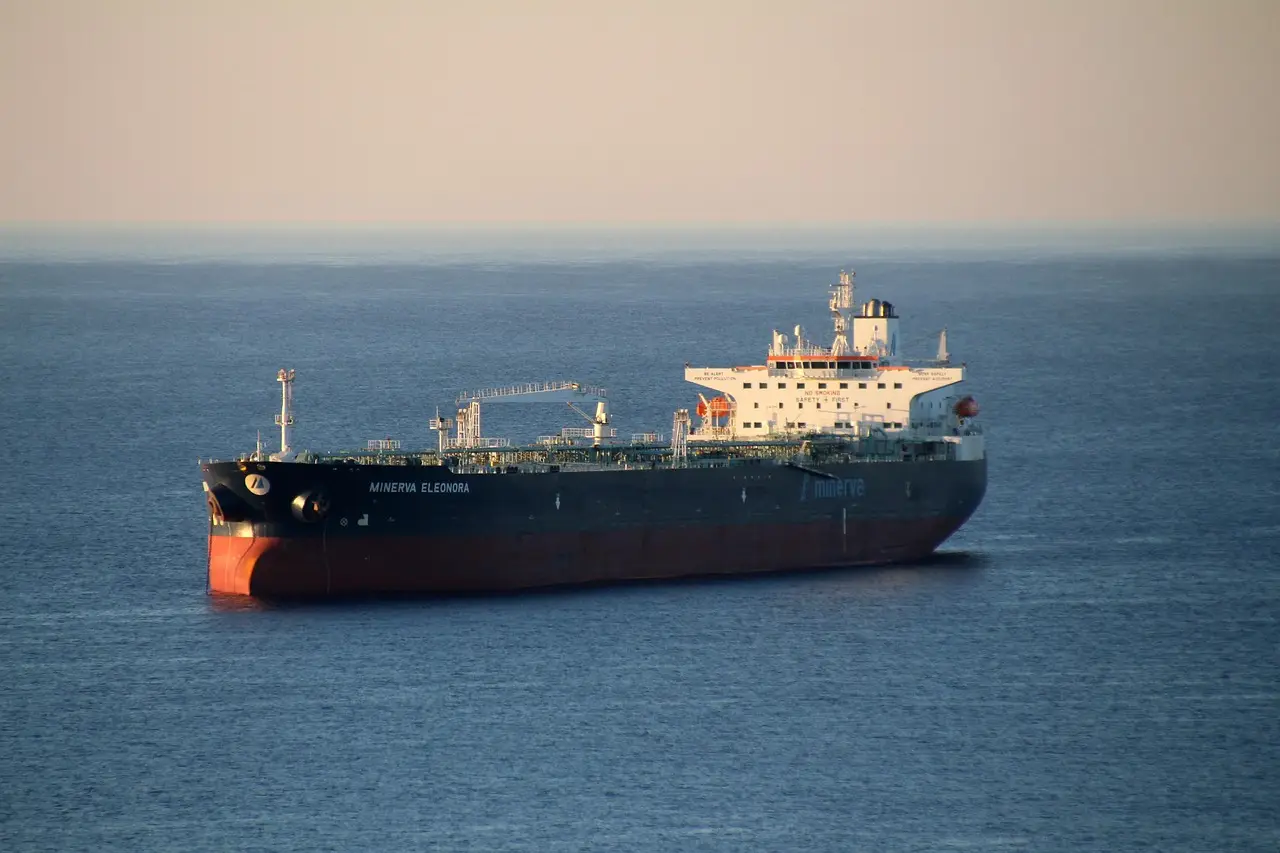
Okeanis Eco Tankers earned $7.67 per share in the third quarter, beating the consensus estimate of $4.73 by $2.94, Zacks reported Wednesday. That's the hardest number in the story, and it's not the only one.
Revenue came in at $501.50 million against a consensus of $220.83 million — more than double what analysts modeled. A year earlier, the Greece-based crude tanker owner earned $0.77 per share. That's a near-tenfold jump in twelve months.
Profitability matched the headline. The company posted a net margin (profit as a share of revenue) of 60.65% and a return on equity of 93.62%. For a shipping firm, those are exceptional prints, and they point to a tanker market running far hotter than most of the market expected.
The simple takeaway: Okeanis didn't just beat estimates, it dwarfed them.
What did the stock do?
Not much, at least on Friday. Shares traded down $0.92 to $86.75 in mid-day trading, on volume of 290,789 shares versus an average of 579,886.
The valuation picture:
- Market capitalization: $3.39 billion
- Price-to-earnings ratio: 4.92
- Beta (sensitivity to market moves): -0.32
- Fifty-day moving average: $85.97
- Two-hundred-day moving average: $60.96
- Fifty-two week range: $31.75 to $102.56
The balance sheet looks solid for the sector. The current ratio (short-term assets over short-term liabilities) stands at 4.43, the quick ratio at 4.13, and debt-to-equity at 0.76.
In plain words: the stock has nearly doubled off its long-run average price, yet still trades below five times earnings.
How big is the dividend?
Bigger. Okeanis declared a quarterly dividend of $7.00 per share, up from $5.25 — a 33.3% increase. That's $28.00 annualized, a yield of 32.3% at recent prices.
Shareholders of record on Monday, November 23 will receive the payment on Tuesday, December 1. The ex-dividend date is also November 23. The payout ratio (dividends as a share of earnings) currently sits at 195.90%, meaning the distribution exceeds reported profit — a deliberate return-of-capital posture common among tanker owners riding strong spot markets.
The takeaway: management is pushing cash out the door as fast as it comes in.
What are analysts saying?
The ratings picture is mixed:
- Zacks Research cut the stock from "strong-buy" to "hold" on Monday, October 5
- Weiss Ratings raised it from "buy (b-)" to "buy (b)" on Wednesday, September 9
- B. Riley Financial lifted its price objective from $100.00 to $120.00 with a "buy" rating on Friday
- Wall Street Zen upgraded from "buy" to "strong-buy" on Saturday, August 8
Two analysts rate the stock a Buy and four rate it a Hold. MarketBeat.com pegs the average rating at "Hold" with a consensus price target of $74.52 — notably below the $86.75 trading price.
In short: sell-side enthusiasm lags the earnings by a wide margin.
What's driving the numbers?
Freight rates. Okeanis said it has covered 71% of its fleet days for the fourth quarter at an average of roughly $420,000 per day — an unusually high locked-in rate that supports expectations for robust near-term revenue and cash flow.
The company operates very large crude carriers (VLCCs, the largest crude tankers afloat) and Suezmax vessels, moving crude between production regions and global markets for energy companies and commodity traders. It deploys the fleet through spot-market voyages and charter arrangements, with ships built to modern efficiency and environmental standards.
The bottom line: with Q4 already largely booked at record-level rates, the cash machine isn't slowing yet.
Audit trail
- Q3 EPS of $7.67 beat the $4.73 consensus by $2.94; revenue of $501.50 million topped a $220.83 million estimate
- Quarterly dividend raised 33.3% to $7.00 per share, payable December 1 to holders of record November 23
- Okeanis has covered 71% of Q4 fleet days at an average of about $420,000 per day
- Net margin was 60.65% and return on equity 93.62% in the quarter
- Consensus rating is Hold with a $74.52 price target versus a Friday price of $86.75
via dailypolitical.com (Source)
More from Grace Kim
Show full bio
Staff writer covering people, launches and day-to-day practice in corporate finance and the leaders who run it at CFO Observer.
232 articles
Cross-references
- Teekay Tankers Beats EPS Estimates by $0.18, Revenue Tops by $105.7 Million
- Okeanis Eco Tankers Books Third Record Quarter, $7 Dividend
- Sea Limited Misses EPS by $0.26 but Revenue Climbs 43.7% to $8.58B
- Viant Technology Posts $0.13 EPS, Tripling the $0.05 Consensus
- Forward Air Posts $0.34 EPS, Beats $0.13 Consensus by $0.21