RefE-824
Entered
Figures3 min · 693 words
Working paper
Trex Lifts Full-Year Outlook After Record Quarter and 26% Sales Jump
Trex raised full-year guidance to $1.296-1.306 billion after record Q3 revenue of roughly $360 million, up 26%, as underlying demand grew about 15% against diesel-driven margin pressure.
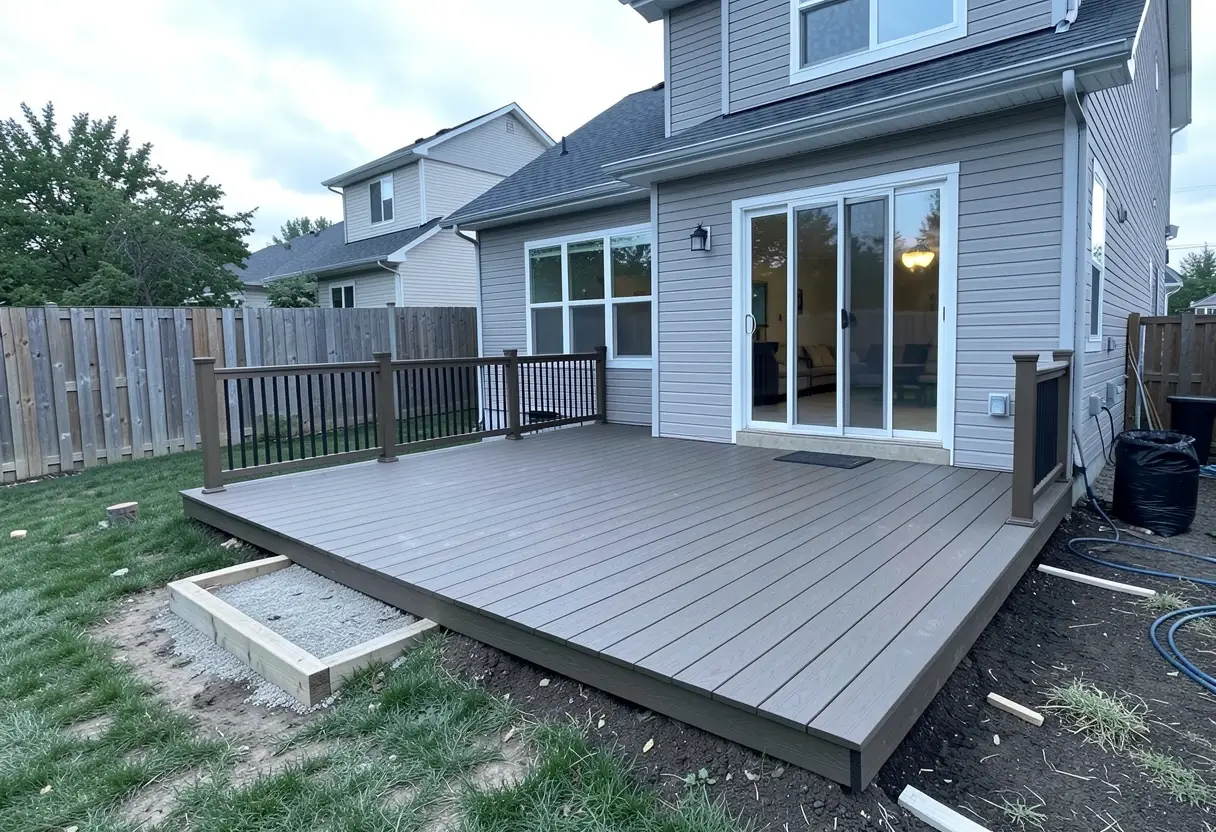
Trex raised its full-year outlook to $1.296 billion to $1.306 billion in net sales after posting approximately $360 million in record third-quarter revenue, a 26% increase driven primarily by volume. The composite decking manufacturer also lifted its full-year adjusted EBITDA (earnings before interest, taxes, depreciation and amortization) guidance to $355 million to $360 million, according to its earnings call.
The new sales outlook represents 11% growth at the midpoint. Chief Financial Officer Prith Gandhi noted that about $30 million of the quarterly increase, or 11 percentage points of growth, came from initial inventory shipments to new distribution partners.
How much of the growth was real demand?
Chief Executive Officer Adam Zambanini estimated that underlying demand grew about 15%, against approximately 6% growth for the overall decking market and 9% for composite decking. He said the distribution load-in was roughly in line with expectations.
"Third-quarter growth was broad-based," Zambanini said, with double-digit gains across entry-level, mid-tier and premium decking. Railing also posted double-digit growth, while fasteners benefited from higher decking sales.
Gandhi estimated that, after adjusting for the load-in and discounting by the former distributor, both quarterly sell-in and sell-out growth were in the teens. On a trailing 12-month basis, the adjusted figures were approximately 8% and 9%, respectively.
What is pressuring margins?
Third-quarter adjusted gross margin came in at 36.9%, down from a year earlier; reported gross margin was 36%. Gandhi cited labor inefficiencies, higher depreciation and freight costs, plus the rapid growth tied to the wood conversion strategy (shifting customers from timber to composite products).
Incremental inbound freight expenses exceeded $4 million in the quarter, primarily on higher diesel prices. Gandhi said adjusted gross margin would have been 38.2% had diesel costs remained comparable to 2025 levels. Trex is discussing a temporary diesel surcharge for its home center business and evaluating longer-term ways to reduce fuel-price exposure.
The margin picture was not uniformly grim. Adjusted gross profit dollars rose 13%, and adjusted EBITDA increased 10% to approximately $100 million, a 27.7% margin. For the full year, Trex expects adjusted gross margin of 37.5% to 38%, adjusted selling, general and administrative expenses of roughly 17% of sales, and capital expenditures of approximately $100 million.
Fourth-quarter sales are guided to $175 million to $185 million, including roughly $5 million of remaining distribution load-in. Zambanini attributed the raised outlook to underlying performance rather than initial shipments. The full-year forecast implies fourth-quarter gross margin of approximately 34% to 35%, with higher production expected to improve fixed-cost absorption.
What happened at Little Rock?
A mechanical issue at the Little Rock, Arkansas, manufacturing facility affected equipment ramp-up and increased startup costs during the quarter. Zambanini said the issue has been resolved and that half of the facility's decking capacity remains on track to be operational by year-end.
Ramp work should continue through the first quarter of 2027, with operations approaching the efficiency of Trex's other plants during the second quarter. Benefits from improved utilization should become more apparent in the second half of 2027, he said.
The company completed initial inventory placements with new distribution partners with minimal disruption. Quarter-end channel inventory was comparable with the prior year, including stock held by the former distributor, and Zambanini reported early conversions from smaller brands through regional distributors.
What about cash and 2027?
Trex generated approximately $135 million in third-quarter free cash flow, repaid $83 million on its revolving credit facility and bought back $55 million of shares. Through Oct. 31, it had repurchased $97 million against a $150 million target for the second half of 2026.
The company did not provide 2027 guidance. Gandhi said margins should improve next year if demand remains healthy and Little Rock reaches network-level efficiency. Zambanini confirmed a 2027 pricing strategy exists but has not communicated its timing; increasing factory volume remains the priority. PVC decking sales remain small, with expanded profiles planned for 2027, and the long-term ambition stands at $2 billion in annual revenue by 2030.
Audit trail
- Trex reported record Q3 net sales of approximately $360 million, up 26% year over year.
- Full-year sales guidance was raised to $1.296-1.306 billion, 11% growth at the midpoint; adjusted EBITDA outlook lifted to $355-360 million.
- Q3 adjusted gross margin fell to 36.9%; it would have been 38.2% absent more than $4 million in incremental diesel-driven freight costs.
- Free cash flow reached approximately $135 million; the company repaid $83 million on its revolver and bought back $55 million of shares.
- Half of the Little Rock facility's decking capacity remains on track to be operational by year-end after a resolved mechanical issue.
via dailypolitical.com (Source)
More from Sophie Lindqvist
Show full bio
Market editor covering technology and product news in corporate finance and the leaders who run it at CFO Observer.
68 articles
Cross-references
- CSX Posts Record $4.02 Billion Quarter on 12% Revenue Jump
- Russel Metals Q3 revenue rises 56% as Kloeckner lifts profit
- Mastercard Q3 Revenue Hits $9.81 Billion, Up 14 Percent
- News Corp Lifts Q1 Revenue 6% to US$2.28 Billion as Net Income Jumps 43%
- Palantir Jumps 12% as U.S. Commercial Revenue Climbs Nearly 150%