RefE-704
Entered
Figures3 min · 682 words
Working paper
Gulfport Energy Targets 20% Cost Cuts, Two-Rig Appalachia Push by 2027
Gulfport Energy targets 20%+ drilling cost cuts by 2028, a two-rig Appalachia program, and raised its buyback authorization 33% to $2 billion on its Q3 call.
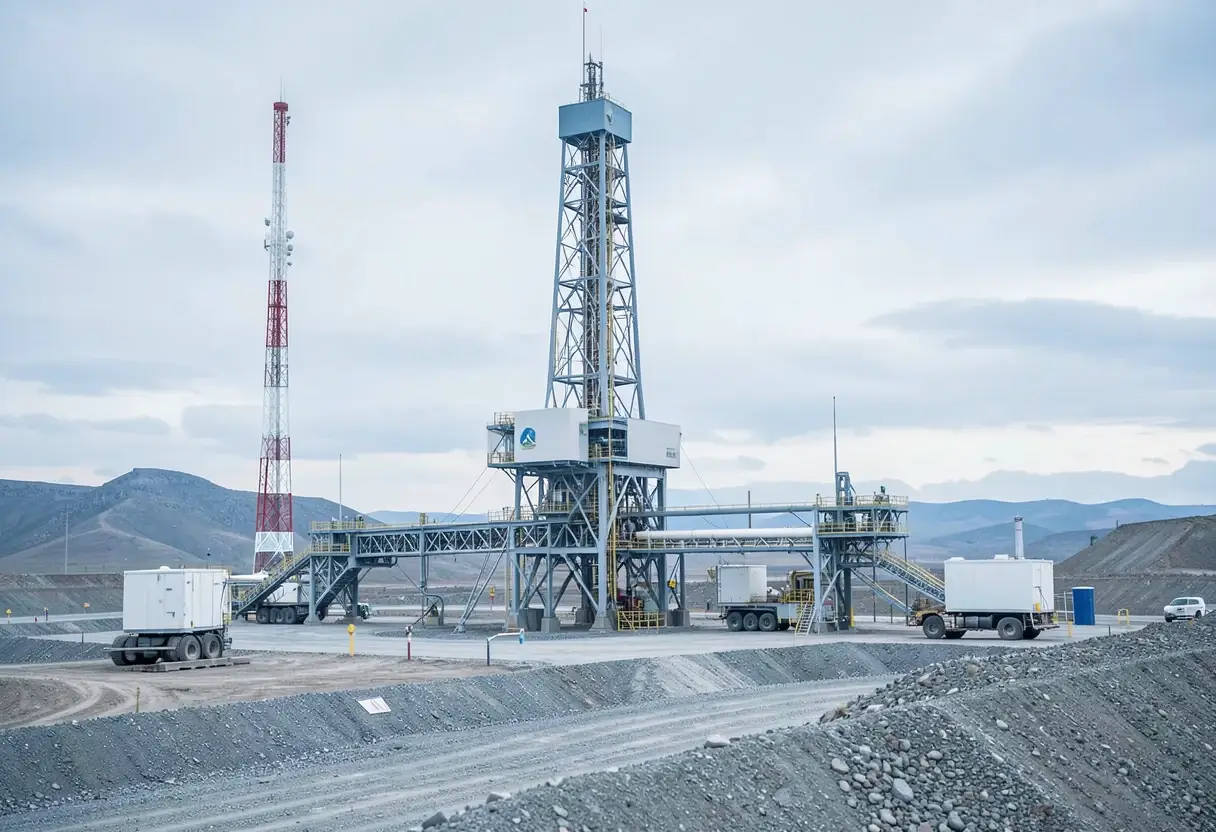
Gulfport Energy (NYSE:GPOR) plans to cut drilling and completion costs per foot by more than 20% between now and 2028, while moving to continuous two-rig operations in Appalachia and reducing Oklahoma activity in 2027. On its third-quarter earnings call, executives said the shift could drive a free cash flow increase in 2028.
President and CEO Nick Dell'Osso said production, capital spending and operating costs were all in line with guidance. Liquids made up 13% of output, supported by recent wet-gas Utica wells brought online. He credited the higher-value production mix, strong realized liquids prices and cost discipline for lifting EBITDA and adjusted free cash flow (cash generated after operating and capital costs) from the second quarter.
What does the 2027 plan look like?
The cost-reduction path combines continuous drilling, development of long-lateral wet-gas pads and an electric fracturing fleet scheduled to begin service in mid-2027. The fleet should cut diesel exposure and completion spending, and Dell'Osso said the more active Appalachian program made the commitment easier to undertake. The commitment runs 18 months, but Gulfport can sublease the fleet or work with the vendor to add other users if activity declines.
Executive Vice President and Chief Operating Officer Matthew Rucker said Gulfport has already folded expected service costs into its 2027 assumptions. Without the planned efficiency gains, the company would have expected roughly 5% inflation in its typical development program, he said.
Gulfport will start 2027 with two rigs, as it typically does, but has not issued formal guidance or committed to a full-year activity schedule. Dell'Osso wants to get through winter, finalize vendor arrangements and prepare pads before releasing guidance alongside fourth-quarter earnings. In short: the plan is set, the budget isn't.
How strong is the cash flow outlook?
The company remains on track to operate within its original 2026 guidance ranges, Dell'Osso said. Gulfport expects adjusted free cash flow to grow more than 15% from 2025 at $3 gas, and it anticipates a double-digit free cash flow yield in 2027 at the same price.
On contracts, Gulfport signed an additional gas supply agreement for the Upper Midwest beginning in the fourth quarter of 2028. Dell'Osso said the deal locks in a more attractive spread to regional pricing points than the company has historically received, while keeping floating exposure to those markets. Together with a 10-year Ohio supply agreement starting in mid-2027, the contracts cover about 10% of forecast Appalachian production over their respective terms. Both use firm transportation capacity Gulfport already holds, and the CEO said the company is open to more agreements if the economics work.
What's happening in Oklahoma and with capital returns?
In Oklahoma's SCOOP region, Gulfport intends to reduce 2027 activity while reviewing development opportunities beyond its historical primary target. Rucker said the company is examining the Springer and Sycamore formations and the deeper, dry-gas portion of the Woodford, including data from wells it participates in on a nonoperated basis. Gulfport has historically drilled the Woodford condensate window.
On acreage, Gulfport closed $83 million of Ohio state land acquisitions in the third quarter and expects to spend another $50 million to $55 million before year-end under its $140 million discretionary program for 2026. It plans to keep pursuing acreage in 2027 but hasn't set a budget.
Shareholder returns got a boost too. Gulfport increased its share repurchase authorization by 33% to $2 billion and has bought back approximately $1.2 billion of stock since the program began. Buybacks will compete for capital with acreage purchases, balance sheet improvements and drilling, Dell'Osso told analysts. Leverage rose in the third quarter after the state land acquisition; he expects it to return to about one times by year-end.
Gulfport, founded in 1997, is an independent exploration and production company focused on natural gas and associated natural gas liquids, concentrated primarily in the Utica Shale in eastern Ohio. The takeaway: a cheaper, more gas-weighted 2027, with cash returns scaling up alongside it.
Audit trail
- Gulfport plans to cut drilling and completion costs per foot by more than 20% by 2028.
- Share repurchase authorization increased 33% to $2 billion; $1.2 billion already bought back.
- Adjusted free cash flow expected to grow more than 15% from 2025 at $3 gas.
- Electric fracturing fleet begins service in mid-2027 under an 18-month commitment.
- $83 million of Ohio state land closed in Q3 under a $140 million 2026 program.
via dailypolitical.com (Source)
More from Grace Kim
Show full bio
Staff writer covering people, launches and day-to-day practice in corporate finance and the leaders who run it at CFO Observer.
113 articles
Cross-references
- Targa Resources sets $6 billion adjusted EBITDA floor for 2026
- Northern Oil and Gas lifts 2026 output outlook as margins recover
- Excelerate lifts Q3 EBITDA to $133M, targets 2027 growth
- 98% of FinOps Teams Now Manage AI Spend, and Allowance Rules Decide the Bill
- Tenaris Guides to 10% Sequential Revenue Rise and 25% EBITDA Margin