RefE-087
Entered
Figures4 min · 812 words
Working paper
Talos Energy Lifts 2026 Output View After Q3 Beat
Talos Energy raised 2026 output guidance about 8% at the midpoint after Q3 production beat, delivering $186 million in adjusted free cash flow on strong Gulf operations.
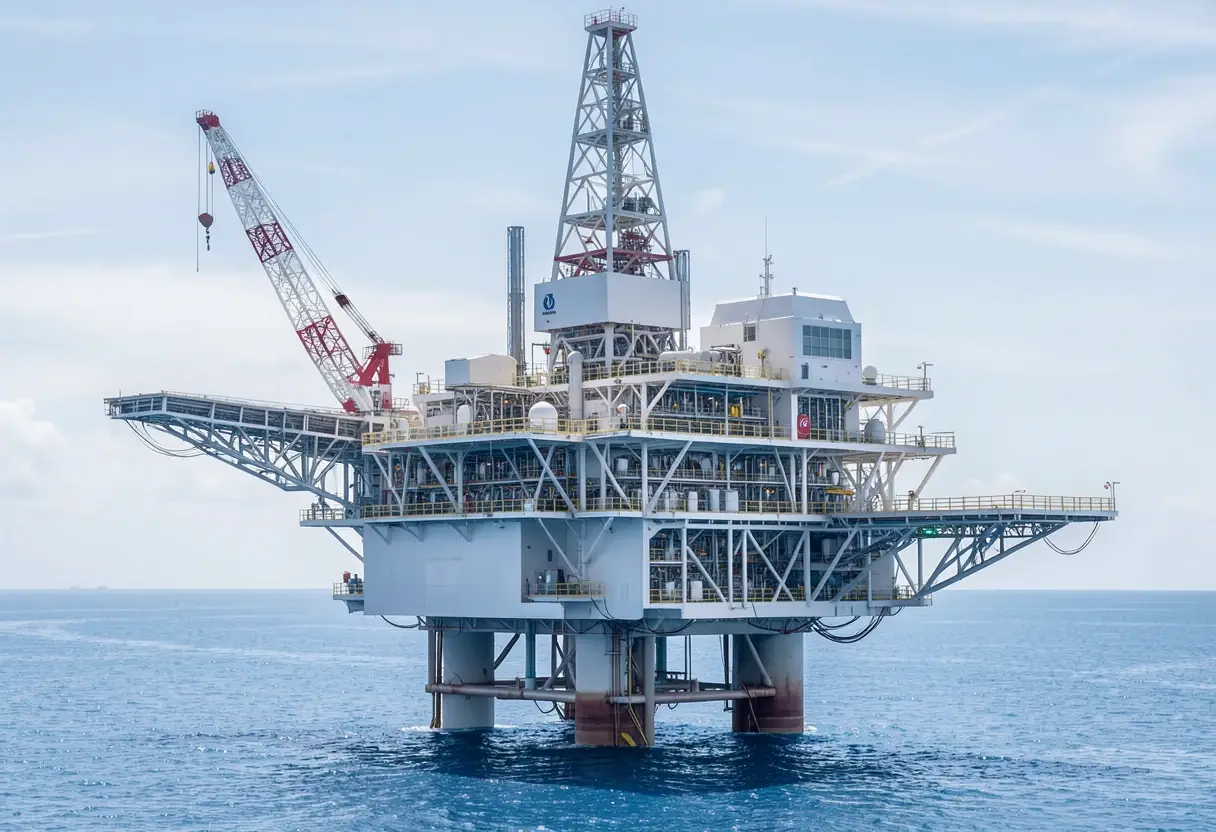
Talos Energy (NYSE:TALO) raised its full-year 2026 production guidance roughly 8% at the midpoint after third-quarter output beat expectations and adjusted free cash flow (operating cash flow minus capital spending) reached $186 million.
The company produced approximately 69,000 barrels of oil per day and 92,000 barrels of oil equivalent per day in the quarter, both above guidance. President and CEO Paul Goodfellow credited strong base operations, no storm-related downtime and an initial contribution from assets acquired on Sept. 22.
Even after adjusting for weather and excluding the acquired assets, production sat at the high end of guidance, Goodfellow said on the Nov. 4 earnings call. Talos also hit its full-year $100 million Optimal Performance Plan cost-savings target by the end of the third quarter.
Takeaway: the quarter outperformed on every operational headline metric the company tracks.
What does the new guidance include?
Talos lifted its 2026 outlook to 68,000–70,000 barrels of oil per day and 92,500–94,500 barrels of oil equivalent per day. At the midpoint, oil production guidance runs approximately 8% above the company's original outlook, Executive Vice President and CFO Zach Dailey said.
The forecast folds in three moving parts:
- The newly closed offshore acquisition
- A completed divestment of non-core, gas-weighted shelf assets
- Fourth-quarter impact from Hurricane Isaias
Goodfellow said the storm cut production by roughly 7,000 barrels of oil equivalent per day during the quarter — within the weather allowance in the annual plan. Talos evacuated offshore personnel and shut in production ahead of the storm; crews found no facility damage after returning.
Takeaway: the raise reflects deals and execution, not just a favorable storm comparison.
What did the financials show?
Third-quarter adjusted EBITDA came in at approximately $406 million. Dailey said oil realizations averaged about $1.60 per barrel above West Texas Intermediate benchmark prices, while lease operating expenses ran $16.74 per barrel of oil equivalent.
On spending, Talos lowered the midpoint of its capital expenditure guidance while raising its outlook for plugging and abandonment spending — leaving combined capital and abandonment outlay unchanged from original guidance. Goodfellow pointed to strong execution in operated projects and the timing of some non-operated projects, including Monument, for the capital forecast. Efficient completion of abandonment work let the company pull additional activity into the fourth quarter.
Takeaway: the capex cut is a timing and efficiency story, not a retreat.
What did the $420 million acquisition add?
Talos closed its Gulf of America acquisition alongside partner Ridgewood for a final net cash purchase price of $420 million. The deal added:
- A 50% working interest and operatorship in the Coulomb field
- A 25% non-operated interest in the BP-operated Na Kika platform and four associated fields
Goodfellow said Talos has identified development and exploration opportunities around the acquired infrastructure, and a Coulomb development well will compete for capital in 2027.
The balance sheet stayed deep. Talos ended the quarter with approximately $410 million in cash, an undrawn credit facility and roughly $1.1 billion in liquidity. Its leverage ratio stood at 0.6 times, and Dailey said Talos expects year-end 2027 leverage to remain well below one times.
The company repurchased 1.4 million shares for approximately $24 million during the quarter, with about $176 million remaining under its authorization. Dailey said the capital allocation framework hasn't changed: return up to 50% of annual free cash flow to shareholders through buybacks while still investing in projects, maintaining balance sheet strength and pursuing selective acquisitions.
Takeaway: the deal was funded without straining liquidity or the buyback commitment.
How are development projects tracking?
- CPN: online since September, performing in line with expectations.
- Brutus: expanded from four wells to five; first oil expected beginning in Q2 2027, with production phased in through Q4.
- Monument: first development well hit approximately 250 feet of net oil pay, in line with pre-drill expectations; a second well began drilling in September; first oil now expected in Q1 2027. Goodfellow said the project's economics are unchanged.
- Daenerys: the appraisal well encountered oil pay in multiple sands, but further work is needed to assess reservoir and fluid properties. A sidetrack is planned for 2027, and Talos is weighing options from a tieback to existing infrastructure to a standalone host.
On timing, Goodfellow said first oil at Daenerys in 2029 was "highly unlikely," though not impossible under a tieback solution. Talos also plans a nearby exploration well in late 2027 or early 2028 that could be co-developed with Daenerys if successful.
In Mexico, Talos is working toward a 2027 final investment decision at Zama and, with Repsol, toward a decision on Block 29 in the second half of 2027. The Block 29 farm-in still needs regulatory approval.
Talos expects to publish its full 2027 outlook in February.
Audit trail
- Q3 adjusted free cash flow was $186 million; adjusted EBITDA approximately $406 million.
- Talos raised 2026 oil guidance to 68,000–70,000 bopd, about 8% above original outlook at midpoint.
- The $420 million Gulf of America acquisition closed Sept. 22, adding Coulomb and Na Kika interests.
- Leverage stood at 0.6 times with $1.1 billion in liquidity; 1.4 million shares repurchased for $24 million.
- Full 2027 outlook expected in February.
via dailypolitical.com (Source)
More from Grace Kim
Show full bio
Staff writer covering people, launches and day-to-day practice in corporate finance and the leaders who run it at CFO Observer.
139 articles
Cross-references
- Northern Oil and Gas lifts 2026 output outlook as margins recover
- MDU Resources Posts $14 Million Q3 as Bakken East Clears FID
- Ameresco guides Q4 EPS above consensus; revenue range spans estimate
- Gulfport Energy Targets 20% Cost Cuts, Two-Rig Appalachia Push by 2027
- GXO Posts Fastest Organic Growth in Three Years, Margins Pay the Price